Senior Citizen Savings Scheme (SCSS): Tax Guide 2026
Senior Citizen Savings Scheme (SCSS) is a government-backed small savings deposit for senior citizens, available at post offices and authorised banks. It pays interest every quarter at a rate notified by the Ministry of Finance: 8.2% a year for October to December 2026, unchanged since 1 April 2023. The deposit qualifies for Section 80C under the old regime, but the interest is fully taxable, and from FY 2025-26 TDS applies only if the interest from one bank or post office exceeds Rs 1,00,000 in the year.
This guide covers SCSS eligibility, tax treatment, TDS deduction, how to claim TDS credit in ITR, and ways to keep tax on SCSS interest low.
What Is SCSS? Eligibility and Terms
Senior Citizen Savings Scheme (SCSS): a 5-year deposit scheme of the Government of India for senior citizens, governed by the Senior Citizens' Savings Scheme, 2019.
Eligibility:
- Resident individuals aged 60 or above
- Retired individuals aged 55 to 60 (and retired defence personnel aged 50 to 60) can also invest their retirement benefits, subject to the scheme's time limits
- Non-resident Indians cannot open an SCSS account
Investment limits:
- Minimum: Rs 1,000 (in multiples of Rs 1,000)
- Maximum: Rs 30 lakh in total across all SCSS accounts of the individual (raised from Rs 15 lakh from 1 April 2023)
- An individual can hold more than one account, and a joint account with a spouse, within the overall limit
Tenure and closure:
- Maturity: 5 years, extendable in blocks of 3 years
- No partial withdrawal is allowed
- Premature closure: before 1 year, interest already paid is recovered from the deposit; after 1 year but before 2 years, 1.5% of the deposit is deducted; after 2 years, 1% of the deposit is deducted
Interest: paid quarterly (not compounded), at the rate notified by the Ministry of Finance for the quarter in which the account is opened. That rate stays fixed for the account's tenure. The rate is 8.2% a year for accounts opened in October to December 2026 (announced on 30 September 2026), the same rate that has applied since 1 April 2023. On the maximum deposit of Rs 30 lakh, that is Rs 61,500 a quarter, or Rs 2,46,000 a year (Rs 30,00,000 x 8.2%). Check the India Post or National Savings Institute website for the rate in the quarter you invest.
Tax status: the deposit qualifies for Section 80C (old regime only); the interest is fully taxable.
Interest Taxation: Schedule OS
SCSS interest is taxed under Income from Other Sources (Schedule OS) in the ITR.
Key points:
- The full interest credited in the year is taxable income, added to total income and taxed at your slab rate
- The deposit (not the interest) qualifies for Section 80C, within the Rs 1,50,000 limit, under the old regime
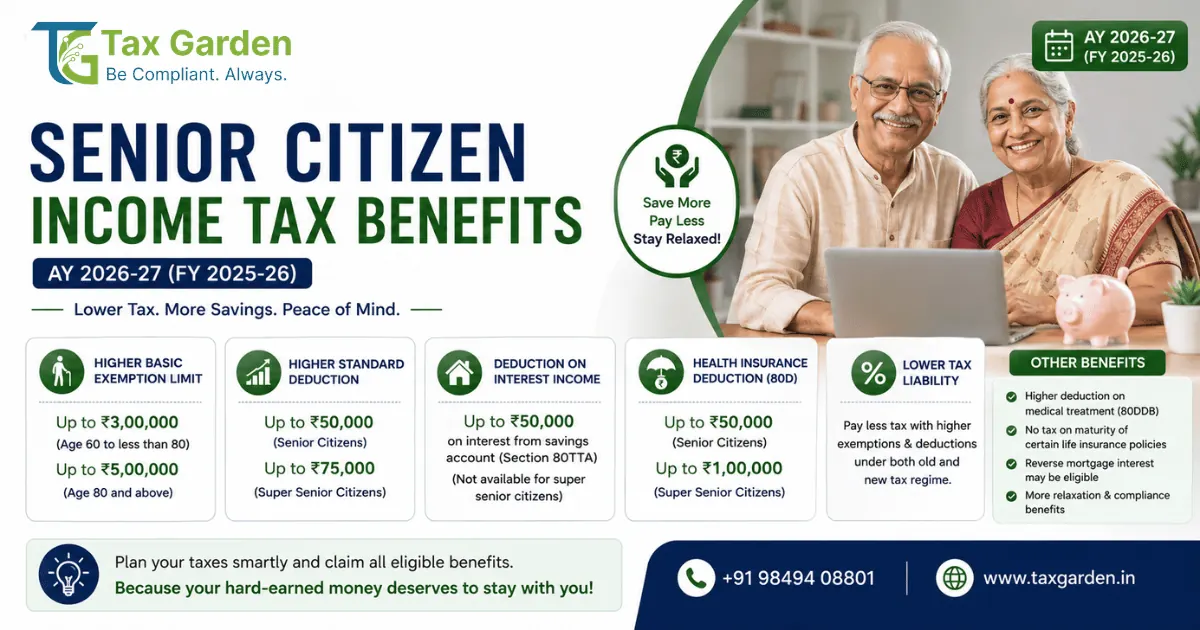
- A resident senior citizen can deduct up to Rs 50,000 of deposit interest (SCSS, FD, RD and savings interest together) under Section 80TTB, under the old regime
- There is no exemption for SCSS interest under Section 10
Example (old regime, 30% slab):
- Annual SCSS interest: Rs 1,50,000
- Less: Section 80TTB (assuming no other deposit interest): Rs 50,000
- Taxable SCSS interest: Rs 1,00,000
- Tax at 30%: Rs 30,000, plus 4% cess of Rs 1,200 = Rs 31,200 (before TDS credit)
TDS Deduction: 10% Rate and Rs 1,00,000 Threshold
TDS rule for FY 2025-26: a bank or post office deducts TDS under Section 194A at 10% (if PAN is furnished) when the interest it pays to a senior citizen in the year exceeds Rs 1,00,000. The threshold was Rs 50,000 until FY 2024-25 and was raised by the Finance Act 2025. From 1 April 2026 the same Rs 1,00,000 threshold for senior citizens continues under Section 393(1) of the Income-tax Act, 2025.
Mechanism:
- TDS is deducted when interest is credited each quarter, once the year's interest is expected to cross the threshold
- The deducted amount appears in your Form 26AS and AIS
Example:
- Annual interest: Rs 1,50,000
- TDS deducted: 10% of Rs 1,50,000 = Rs 15,000
- Interest paid to you: Rs 1,35,000
If interest from that bank or post office is Rs 1,00,000 or less: no TDS is deducted, but the interest is still taxable.
Form 16A: the bank or post office issues a TDS certificate in Form 16A for FY 2025-26 (Form 131 from tax year 2026-27).
Avoiding TDS: Form 15H
If the tax on your estimated total income for the year (including SCSS interest) is nil, you can submit Form 15H to the bank or post office so that no TDS is deducted. Form 15H is only for resident individuals aged 60 or above. From 1 April 2026, under the Income Tax Act 2025 and the new rules, the declaration is made in Form 121 instead.
Steps:
- Get Form 15H from the bank or post office (many banks accept it online)
- Fill in your name, PAN, account details and estimated total income for the year
- Declare that the tax on your estimated total income is nil
- Submit it at the start of each financial year, before the first interest credit
- The bank or post office will not deduct TDS while a valid Form 15H is on file
Condition: the declaration must be true. A false declaration can attract penalty and prosecution, and the interest remains taxable if your income turns out to be higher.
Reporting in ITR: Schedule OS
When filing ITR for AY 2026-27:
Schedule OS:
- Report SCSS interest under interest income (other interest)
- Amount: the full interest credited in FY 2025-26, before TDS, matching your AIS
Schedule TDS2:
- TDS credit is pre-filled from Form 26AS where the bank or post office has reported it
- Claim the full TDS credit
Example ITR entry (continuing the example above, old regime):
- SCSS interest (gross): Rs 1,50,000
- Section 80TTB deduction: Rs 50,000
- Tax on the Rs 1,00,000 balance at 30% plus cess: Rs 31,200
- TDS credit claimed: Rs 15,000
- Balance tax payable: Rs 16,200
SCSS vs PPF for Senior Citizens
Key insight: PPF interest is tax-free and has no TDS; SCSS interest is taxable. For a senior citizen with high total income, PPF is more tax-efficient, while SCSS gives regular quarterly income.
Maturity and Extension
At maturity (5 years):
- The deposit is repaid with the final quarter's interest
Extension: the account can be extended for a further block of 3 years by applying within one year of maturity, at the rate applicable on the date of maturity.
If not extended: the account is closed and no further interest accrues.
Key Takeaways for Action
- Report SCSS interest in Schedule OS of your ITR.
- Claim TDS credit in Schedule TDS2 (if TDS was deducted).
- Submit Form 15H (Form 121 from 1 April 2026) if tax on your estimated total income is nil.
- Claim Section 80C on the deposit and 80TTB on the interest if you file under the old regime.
- Keep Form 16A from the bank or post office for the TDS credit.
Sources: Department of Posts, Senior Citizens' Savings Scheme, 2019 and amendments; Ministry of Finance small savings interest rate announcement for October to December 2026; Income Tax Act 1961 Sections 80C, 80TTB and 194A (threshold raised to Rs 1,00,000 for senior citizens by the Finance Act 2025); Income-tax Act 2025 Section 393; Form 15H and Form 121; Schedule OS and TDS2 reporting in the ITR.