Key Takeaways
- From 1 April 2026, salary TDS is governed by Section 392 of the Income-tax Act, 2025 (old Section 192). The employer deducts tax at the average rate on the employee's estimated salary income for the tax year.
- Salary TDS for April to February is deposited by the 7th of the next month; TDS deducted in March is due by 30 April (Rule 218 of the Income-tax Rules, 2026).
- The quarterly salary TDS statement is now Form 138 (old 24Q), due 31 July, 31 October, 31 January and 31 May. The annual certificate is Form 130 (old Form 16), due by 15 June.
- Under the new regime (the default under Section 202), HRA, LTA and the professional tax deduction are not allowed. The standard deduction is Rs 75,000, and the Section 156 rebate makes tax nil up to Rs 12 lakh of total income.
- HRA exemption (old regime only) is the least of actual HRA, rent minus 10% of salary, and 50% of salary in Mumbai, Kolkata, Delhi, Chennai, Hyderabad, Pune, Ahmedabad and Bengaluru (40% elsewhere).
- Arrears relief (old Section 89) is now Section 157, claimed through Form 39 (old Form 10E).
This resource walks through the payroll cycle for employers in India: how CTC becomes take-home pay, how salary TDS is worked out and deposited, the quarterly statement and annual certificate, and the exemptions and claims an employer has to document. It is written for SME owners, HR teams and accountants who run payroll in-house or through an outsourced provider. All section numbers refer to the Income-tax Act, 2025 and the Income-tax Rules, 2026, which apply from tax year 2026-27 (1 April 2026 onwards), with the old 1961 Act section shown in brackets where it helps.
Part 1: From CTC to Take-Home Salary
What CTC Includes
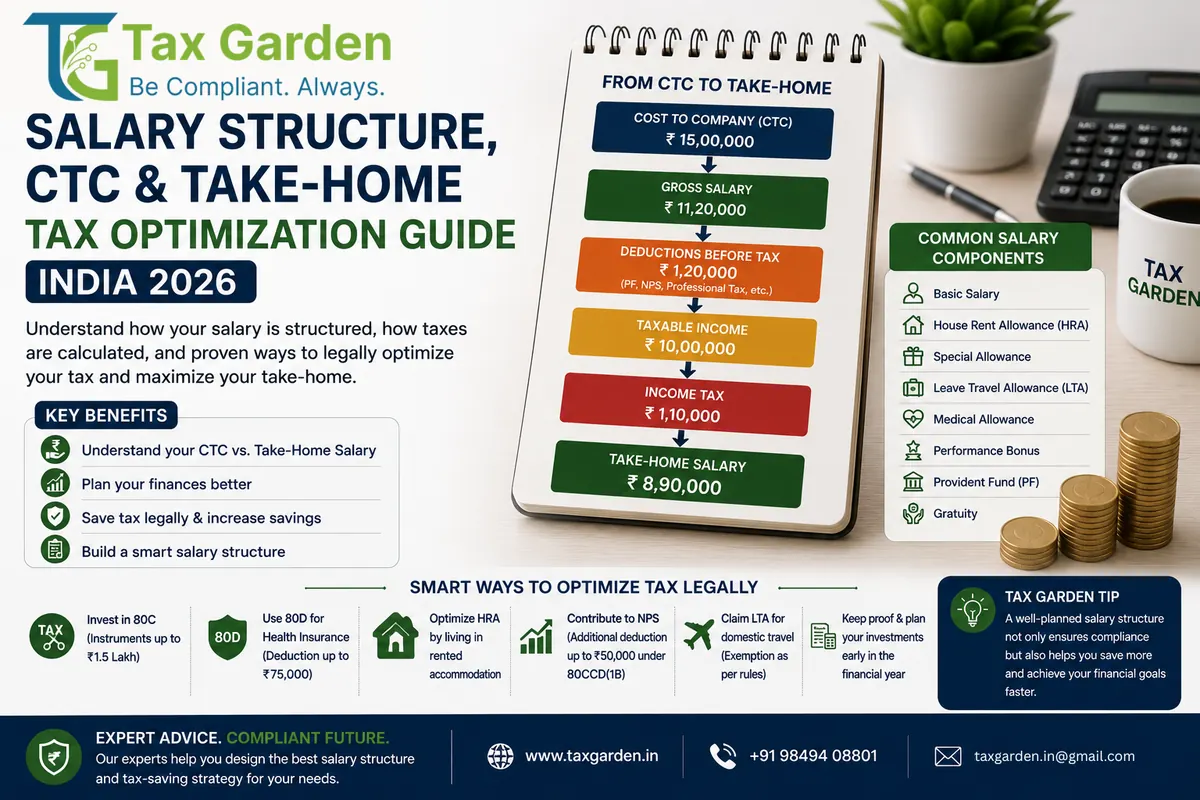
CTC (cost to company) is everything the employer spends on an employee in a year:
CTC = Gross salary + Employer PF and ESI contributions + Gratuity provision + Other employer-paid benefits
Take-home pay = Gross salary - Employee PF - Employee ESI (if covered) - Professional tax - Salary TDS
PF, ESI and professional tax rates and wage ceilings come from labour and state law, not the Income-tax Act. Our payroll compliance service covers those filings.
How Common Salary Components Are Taxed
| Component | Old regime | New regime (Section 202, default) |
|---|---|---|
| Basic pay and DA | Taxable | Taxable |
| House rent allowance (HRA) | Partly exempt (Schedule III, Sl. No. 11; Rule 279) | Fully taxable |
| Leave travel concession (LTC) | Exempt for actual fare, two journeys in a block of four calendar years (Schedule III, Sl. No. 8; Rule 278) | Fully taxable |
| Professional tax paid by employee | Deductible (Section 19(1), Sl. No. 1) | Not deductible |
| Standard deduction | Rs 50,000 | Rs 75,000 (Section 19(1), Sl. No. 2) |
| Employer contribution to notified pension scheme (NPS) | Deductible up to 10% of salary (14% for government employers) under Section 124(1) | Deductible up to 14% of salary under Section 124(2) |
| Employer contributions to PF, NPS and superannuation above Rs 7,50,000 in aggregate | Taxable perquisite (Section 17(1)(h)) | Taxable perquisite |
| Gratuity on retirement or termination | Exempt within the limits in Section 19(1), Sl. Nos. 3 to 6 | Same |
| Performance bonus, special allowance | Taxable | Taxable |
The old conveyance allowance (Rs 1,600 a month) and medical reimbursement (Rs 15,000 a year) exemptions no longer exist; they were replaced by the standard deduction years ago, so do not build them into a salary structure.
HRA Exemption (Old Regime Only)
Under Rule 279 of the Income-tax Rules, 2026, the exempt part of HRA is the least of:
- Actual HRA received for the period
- Rent paid minus 10% of salary for the period
- 50% of salary if the employee lives in Mumbai, Kolkata, Delhi, Chennai, Hyderabad, Pune, Ahmedabad or Bengaluru; 40% anywhere else
"Salary" here means basic pay plus DA (where the terms of employment count DA), and excludes other allowances. Hyderabad, Pune, Ahmedabad and Bengaluru moved to the 50% list under the 2026 Rules; see our note on the new 50% HRA cities.
Example (Hyderabad, old regime): basic Rs 50,000 a month, HRA Rs 30,000, rent Rs 35,000.
- Actual HRA = Rs 30,000
- Rent minus 10% of basic = Rs 35,000 - Rs 5,000 = Rs 30,000
- 50% of basic (Hyderabad) = Rs 25,000
Exempt HRA = Rs 25,000 a month; taxable HRA = Rs 5,000 a month.
Points employers often get wrong:
- An employee who lives in a house they own cannot claim HRA for it. An employee who owns a house in another city and pays rent where they work can claim both HRA and home loan interest.
- The landlord's name, address and PAN must be collected where annual rent exceeds Rs 1,00,000 (Rule 205 table, Sl. No. 1).
LTC (Old Regime Only)
Rule 278 limits the exemption to the actual fare for travel within India: the air fare for the class the employee is entitled to, by the shortest route, if travelling by air; AC first-class rail fare where the places are connected by rail and another mode is used; and first or deluxe class public transport fare (or Rs 30 per km where no public transport exists) otherwise. Hotel stays, meals and local sightseeing are not covered.
The exemption is available for two journeys in a block of four calendar years, counted from calendar year 2022, so the current block is 2026 to 2029. A journey not used in one block can be taken in the first calendar year of the next block without counting against that block's two journeys. It covers the employee's family, but not more than two surviving children; this limit does not apply to children born before 1 October 1998 or to multiple births after the first child.
Gratuity
Gratuity is taxed when it is paid, not while the employer provides for it. On retirement or termination:
- Government employees: fully exempt (Section 19(1), Sl. No. 3).
- Employees covered by the Payment of Gratuity Act: exempt up to the amount worked out under Section 4(2) and (3) of that Act (15 days' wages for each completed year of service, with wages divided by 26), subject to the Rs 20 lakh ceiling (Sl. No. 5).
- Other employees: exempt up to the least of the amount received, the notified ceiling (Rs 20 lakh) and half a month's average salary for each completed year (Sl. No. 6).
For worked examples, see our gratuity tax exemption guide.
Part 2: Monthly Salary TDS
How the Employer Works Out TDS
Section 392(1) requires the employer to deduct tax at the average rate on the employee's estimated salary income for the whole tax year. In practice:
- Estimate the year's taxable salary after the standard deduction and any claims the employee has proved.
- Compute tax at the slab rates of the regime the employee will use, apply the Section 156 rebate if eligible, and add 4% cess (and surcharge where income is high).
- Spread the tax over the remaining months of the year. Section 392(5)(c) lets the employer increase or reduce later deductions to correct any excess or shortfall.
Example 1 (new regime): annual salary Rs 9,00,000.
- Taxable salary = Rs 9,00,000 - Rs 75,000 = Rs 8,25,000
- Tax = 5% of Rs 4,00,000 + 10% of Rs 25,000 = Rs 22,500
- Section 156(2) rebate (total income up to Rs 12 lakh) = Rs 22,500
- Tax and monthly TDS = nil
Example 2 (new regime): annual salary Rs 18,00,000.
- Taxable salary = Rs 18,00,000 - Rs 75,000 = Rs 17,25,000
- Tax = Rs 20,000 (4-8 lakh) + Rs 40,000 (8-12 lakh) + Rs 60,000 (12-16 lakh) + Rs 25,000 (20% of Rs 1,25,000) = Rs 1,45,000
- Cess at 4% = Rs 5,800; total Rs 1,50,800
- Monthly TDS = about Rs 12,567
What the Employee Gives the Employer
| Form (Rules 2026) | Old form | Purpose |
|---|---|---|
| Form 124 | 12BB | Evidence of claims: HRA (landlord PAN above Rs 1 lakh rent), LTC, home loan interest, Chapter VIII deductions |
| Form 122 | 12B | Salary from other employers in the same year, other income, house property loss, other TDS (optional, Section 392(4)) |
| Form 39 | 10E | Particulars for arrears relief under Section 157 |
The employer gives the employee Form 123 (old 12BA) with perquisite details where salary for the year exceeds Rs 1,50,000 (Rule 204(2)).
If an employee does not say which regime they will use, compute TDS under the new regime, which is the default under Section 202(1). The employee's final choice is made in the return. Our Form 12BB investment declaration guide explains the proofs from the employee's side.
Depositing the Tax
Under Rule 218(2) of the Income-tax Rules, 2026, a non-government employer must deposit salary TDS:
- By the 7th of the following month for tax deducted from April to February
- By 30 April for tax deducted in March
TDS is paid online through the e-Pay Tax service on the income tax e-filing portal using the employer's TAN.
Interest and Fees for Delay
- Late deduction: 1% a month or part of a month from the date tax was deductible to the date it is deducted (Section 398(3)(a)(i)).
- Late deposit after deduction: 1.5% a month or part of a month from the date of deduction to the date of payment (Section 398(3)(a)(ii)). This interest must be paid before the quarterly statement is filed.
- An employer who fails to deduct or deposit is treated as an assessee in default (Section 398(1)) and may also face a penalty under Section 448.
Part 3: Quarterly Statement and Annual Certificate
Form 138 (Old Form 24Q)
Salary TDS is reported every quarter in Form 138 under Rule 219 of the Income-tax Rules, 2026. Each statement lists every employee's PAN, salary paid, tax deducted and challan details; the Q4 statement also carries the full-year salary breakup.
| Quarter | Period | Due date (Rule 219(4)) |
|---|---|---|
| Q1 | April to June | 31 July |
| Q2 | July to September | 31 October |
| Q3 | October to December | 31 January |
| Q4 | January to March | 31 May |
Late filing:
- Fee: Rs 200 a day until the statement is filed, capped at the tax deductible, paid before filing (Section 427).
- Penalty: Rs 10,000 to Rs 1,00,000 for late filing or incorrect details (Section 461). No penalty for delay applies if the tax, fee and interest were paid and the statement was filed within one month of the due date.
Form 130 (Old Form 16)
The annual salary TDS certificate is Form 130, issued by 15 June after the end of the tax year. It must match the Q4 Form 138, so file and correct the statement first. See our explainer on Form 130 replacing Form 16.
Part 4: Arrears Relief (Old Section 89, Now Section 157)
When an employee receives arrears or advance salary, salary for more than twelve months in one year, profits in lieu of salary, or arrears of family pension, the lump sum can push them into a higher slab. Section 157 lets the tax be recomputed as if the amount had been received in the years it relates to, and the extra tax caused by bunching is given as relief.
- The employee furnishes the particulars in Form 39 by the return due date (Rule 73(3) of the Income-tax Rules, 2026).
- An employee of a company, co-operative society, local authority, university or similar body may give the Form 39 particulars to the employer, who then allows the relief while computing TDS (Section 392(4)(a)(ii)).
- No relief is available on an amount for which the employee has claimed a deduction under Section 19(1), Sl. No. 12.
For a worked example from the employee's side, see our Section 89 relief and Form 10E guide.
Part 5: Employer Compliance Calendar
| When | What | Rule or section |
|---|---|---|
| Start of the tax year | Collect each employee's intended regime and any Form 122 particulars | Section 392(4) |
| By the 7th of each month | Deposit salary TDS for the previous month | Rule 218(2)(b) |
| Before the final quarter | Collect Form 124 proofs (rent, LTC, investments) | Rule 205 |
| 30 April | Deposit TDS deducted in March | Rule 218(2)(a) |
| 31 May | Q4 Form 138 | Rule 219(4) |
| 15 June | Issue Form 130 (and Form 123 where needed) | Rules 204 and 215 |
| 31 July | Q1 Form 138 | Rule 219(4) |
| 31 October | Q2 Form 138 | Rule 219(4) |
| 31 January | Q3 Form 138 | Rule 219(4) |
Part 6: Common Payroll Mistakes
| Mistake | What happens | Fix |
|---|---|---|
| Allowing HRA or LTC to an employee on the new regime | Short deduction and 1% a month interest | Confirm the regime before allowing any exemption |
| Depositing TDS after the 7th | 1.5% a month interest from the date of deduction | Deposit with the salary run |
| Filing Form 138 late | Rs 200 a day fee, possible Section 461 penalty | File within the month after each quarter |
| Form 130 not matching Form 138 | Employee's credit and return do not match | Correct the statement before issuing certificates |
| Allowing HRA without landlord PAN (rent above Rs 1 lakh) | Exemption not supported by evidence | Collect Form 124 with landlord details |
| Still budgeting conveyance or medical reimbursement as exempt | Under-deduction | Treat both as taxable salary |
Conclusion
Payroll tax compliance comes down to four things done on time: the right regime and claims for each employee, monthly deposits by the 7th, four Form 138 statements, and Form 130 certificates by 15 June. Getting the salary structure right at the start of the year makes each of those simpler.
Tax Garden's payroll services cover monthly TDS calculation and deposit, quarterly Form 138 statements, annual Form 130 certificates and Form 39 support for arrears. We provide filing and compliance execution only, not salary structure design or tax planning. For monthly payroll processing see our payroll management service, and for PF, ESI, professional tax and TDS returns see our payroll compliance service.
Sources
Income-tax Act, 2025 as amended by the Finance Act, 2026 (Sections 17, 19, 124, 156, 157, 202, 392, 398, 427, 448, 461; Schedule III, Sl. Nos. 8 and 11) and the Income-tax Rules, 2026 (Rules 204, 205, 215, 218, 219, 278 and 279, and Rule 73 with Form 39), both from incometaxindia.gov.in. Payment of Gratuity Act, 1972, Section 4.