GST on Domestic Tour Packages: Overview
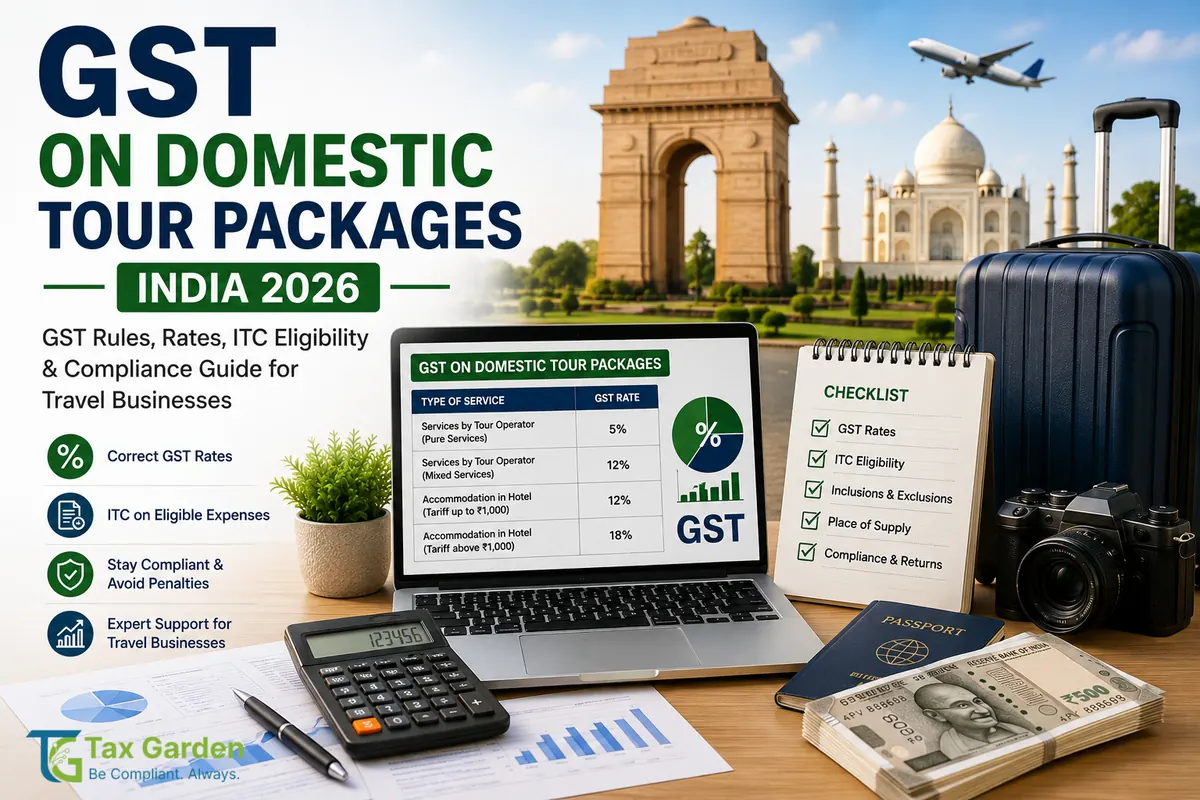
Tour operator services in India are taxed under Notification 11/2017-CT(Rate). Two options are available:
- 5% rate: 5% GST on the gross package amount, with no ITC except on tour operator services bought from another tour operator
- 18% rate: 18% GST on the package, with full ITC
Tour operator chooses which method suits business model.
5% Package Rate Scheme
Eligibility
- Tour operator bundles two or more services (hotel, transport, sightseeing, meals)
- Entire package priced as single offering
- Invoice shows the gross amount charged, including hotels, transport and sightseeing
Rate
- 5% GST on entire package consideration
- Applied on package value, not components separately
- Example: Rs 50,000 package = Rs 2,500 GST
Mandatory Condition
- No ITC claim on inputs (hotel bills, transport, activity costs, office rent)
- The only exception is ITC on tour operator services bought from another tour operator
- Mutually exclusive: operator either takes the 5% rate OR charges 18% and claims ITC
When to Opt
- Low ITC benefit (minimal input costs)
- Transparent pricing for customers
- Simplified compliance
The 18% Option With ITC
If the tour operator does NOT use the 5% rate, the whole package is taxed at 18% and the operator can claim ITC. The package is not split into components with separate rates.
When to Use the 18% Option
- High taxable input costs (significant ITC available)
- Mostly business (B2B) customers who can claim the 18% back
- ITC on inputs is worth more than the 13 percentage point higher rate
ITC Eligibility
- ITC available on hotels, transport and other inputs used to supply the package
- Food and beverages are blocked under Section 17(5), except where used to make an outward supply of the same category or as part of a taxable composite or mixed supply
Air Tickets Within a Package
- A tour operator who opts for the 5% rate (without ITC) charges 5% on the gross package value, including any air ticket bundled into the package.
- Air tickets sold on their own are taxed by the airline: 5% for economy class and 18% for other classes after GST 2.0.
- If the operator only books a ticket as an agent and the fare is paid through to the airline, the fare is not part of the operator's supply. GST applies only to the operator's service fee or commission.
Example
- Package: Rs 50,000 (hotel Rs 20,000 + flight Rs 25,000 + activities Rs 5,000)
- Under the 5% option: GST = 5% of Rs 50,000 = Rs 2,500, and the operator cannot claim ITC on the hotel, flight or activity costs.
Domestic vs Inbound Packages
Domestic Packages (Indian tourists)
- Subject to 5% (no ITC) or 18% (with ITC)
- Charged within India
- ITC available only under the 18% option
Inbound Packages (Foreign tourists)
- Tours performed in India are not exports, even when paid in foreign currency
- Place of supply of services that need the traveller's physical presence is where they are performed (Section 13(3)(b) of the IGST Act), which is India
- GST applies at 5% or 18%, as for domestic customers
- Only the part of a tour conducted wholly outside India for a foreign tourist is exempt from IGST
Key Difference
Where the tour is performed decides the tax, not the tourist's nationality or the currency of payment.
E-Commerce Platform TCS Obligation
Online travel platforms (MakeMyTrip, Goibibo, Yatra, Cleartrip) collect 0.5% TCS (0.25% CGST + 0.25% SGST, or 0.5% IGST) from tour operators under Section 52 of the CGST Act. The rate was cut from 1% with effect from 10 July 2024.
Mechanism
- Platform collects 0.5% TCS on the net taxable value of supplies made through it
- TCS paid to government
- Tour operator accepts the TCS credit on the portal and uses it from the electronic cash ledger
Example
- Tour operator sells Rs 50k package via MakeMyTrip
- Platform collects Rs 250 (0.5% TCS)
- Operator nets Rs 49,750
- Operator uses the Rs 250 credit towards its GST liability
Platforms Subject to TCS Rule
- Online travel aggregators
- E-commerce operators facilitating tour sales
- B2B portals connecting operators to customers
Worked Example: Rs 50k Domestic Package
Scenario: Operator sells 3-day Goa package (hotel 2 nights, car rental, sightseeing).
Component Pricing:
- Hotel (2 nights): Rs 20,000
- Sightseeing/activity: Rs 15,000
- Car rental (transport): Rs 10,000
- Meals: Rs 5,000
- Total: Rs 50,000
Option 1: 5% Package Scheme
- GST @5%: Rs 50,000 × 5% = Rs 2,500
- Total cost to customer: Rs 52,500
- No ITC on input costs
- Operator pays the full Rs 2,500 GST in cash
Option 2: 18% With ITC
- GST @18%: Rs 50,000 × 18% = Rs 9,000
- Total cost to customer: Rs 59,000
- ITC available on GST charged by hotels, transport and other suppliers (meals blocked under Section 17(5))
Comparison: the 5% option costs the customer Rs 6,500 less GST but gives the operator no ITC. The 18% option suits operators selling mainly to businesses that can claim the credit.
Compliance Checklist for Tour Operators
GST Registration
- Register if aggregate turnover exceeds Rs 20 lakh (Rs 10 lakh in special category States such as Manipur, Mizoram, Nagaland and Tripura)
- Use the SAC for tour operator services on invoices
Invoice Requirements (if 5% scheme)
- Mention "Package rate 5% GST" or similar
- Show total package value
- Show GST amount (5% of total)
- Invoice date, number, tour operator details
GSTR Returns
- GSTR-1: Report packaged service supplies
- GSTR-3B: Report GST liability (5% if package scheme, component rates if opted)
- Monthly filing, or quarterly under QRMP if aggregate turnover is up to Rs 5 crore
Input Documentation
- If 5% scheme: Keep bills but note ITC is not claimed
- If component scheme: Maintain GST invoices from suppliers (hotel, transport, activity providers)
e-Invoicing
- Mandatory for B2B invoices if aggregate turnover exceeded Rs 5 crore in any year (since 1 August 2023)
- Not required below that
TCS Management (e-commerce sales)
- Track 0.5% TCS collected by platforms
- Accept the TCS credit on the portal and match it with platform statements
Common Pitfalls and Penalties
Pitfall 1: Bundling Air Tickets at 5%
- Error: Including standalone airline charges in 5% package
- Risk: A fare bundled into the package price becomes part of the gross package value and is taxed at the package rate
- Fix: Where you only book the flight as a pure agent, show the exact fare separately on the invoice (the airline charges 5% for economy and 18% for other classes)
Pitfall 2: Claiming ITC After Opting for 5% Scheme
- Error: Deducting input GST while charging customer 5% package rate
- Penalty: Demand under Section 73 or 74 (Section 74A from FY 2024-25) with interest at 18% per annum under Section 50
- Fix: Decide clearly between the 5% rate (no ITC) and the 18% rate (ITC available), and apply it consistently
Pitfall 3: Not Filing TCS Credit
- Error: Platform collects 0.5% TCS but operator doesn't accept and use the credit
- Penalty: TCS not credited, operator overpays GST
- Fix: Reconcile platform statements with the TCS credit shown on the portal every month
Pitfall 4: Treating Foreign Tourist Packages as Exports
- Error: Charging no GST on tours in India sold to foreign tourists
- Penalty: Demand + interest if discovered in audit
- Fix: Charge GST on tours performed in India; only the part of a tour conducted wholly outside India for a foreign tourist is exempt
Source: CGST Act 2017 (Sections 17(5), 50, 52), IGST Act Section 13(3)(b), Notification 11/2017-CT(Rate) as amended, CBIC FAQs on the 56th GST Council decisions